Harvard endowment jumps 27% in best year since 2021, SpaceX top holding
A 27% return, the strongest since 2021, shows how private-market stakes like SpaceX are reshaping elite endowment portfolios.
Harvard University's endowment returned 27% in fiscal 2026, its best performance since 2021, with SpaceX becoming its top holding. The gain underscores the growing reliance of large institutional investors on private, high-growth companies to drive outsized returns.
Harvard University's endowment jumped 27% in fiscal 2026, marking its strongest annual return since 2021, according to the university's latest financial report. The surge was powered by SpaceX, the private rocket company, which now stands as the endowment's top holding. The 27% gain is a striking reversal from the prior year's more modest performance and underscores how a concentrated bet on a single private company can move the needle for even the largest institutional portfolios.
For Harvard, the return translates into a significant boost to the university's operating budget, which relies on the endowment to fund financial aid, research, and faculty salaries. While the university did not disclose the exact dollar figure, a fund of Harvard's scale - historically one of the largest in the world - can see its value increase by billions of dollars on a 27% return. The performance also signals that Harvard Management Company's long-standing strategy of allocating heavily to private markets is paying off, even as public markets have been volatile.
SpaceX, the private space exploration company, has become a cornerstone of the endowment's portfolio. The company, which has not yet gone public, has grown into a dominant player in commercial spaceflight, launching satellites and crewed missions for NASA and private customers. For Harvard, holding SpaceX as its top position reflects a broader trend among elite endowments: increasingly, the biggest returns come not from public stocks and bonds, but from private companies that stay private longer and deliver outsized growth before any IPO.
The result is a benchmark for other institutional investors. University endowments, foundations, and pension funds closely watch Harvard's annual performance as a gauge of what is possible in the current market. The 27% return - the best since 2021 - suggests that private-market exposure, particularly to high-growth technology and space companies, remains a powerful driver of outperformance. But it also raises the bar for peers who may not have the same access to top-tier venture funds or the ability to underwrite complex private deals.
There are risks, however. Concentrated positions in a single private company can create significant volatility and valuation uncertainty. Private companies are typically marked to market based on the latest funding rounds or internal estimates, which can lag reality. Regulators, including the SEC, have been scrutinizing how private funds value their holdings, and any changes to disclosure requirements could affect how endowments report performance. Harvard's reliance on SpaceX also exposes the fund to the fortunes of one company, which could face regulatory, competitive, or technological setbacks.
For university leadership, the windfall will likely ease budget pressures and support strategic initiatives. Harvard has faced scrutiny over its financial aid policies and its endowment's tax-exempt status, and a strong return provides ammunition for defenders of the university's investment approach. At the same time, the concentration risk inherent in a top holding like SpaceX should prompt a closer look at portfolio construction and stress-testing. Investment committees at other institutions may ask whether their own portfolios are too dependent on a handful of private winners.
The strategic stakes extend beyond Harvard. For chief investment officers and finance chiefs, the lesson is that access to high-quality private deals is becoming a competitive advantage. Those without such access may need to partner with specialized funds or reconsider their asset allocation. The 27% return also resets expectations: stakeholders may now demand similar performance, even though such returns are historically rare. The challenge is to balance the pursuit of outsized gains with the discipline to manage concentration and liquidity risk.
This story's Key Insights and Take-aways are locked.
Create a free account to unlock Executive Actions for one credit.
Register to UnlockAlways free for Executives Club members. Join the Club
More in Business
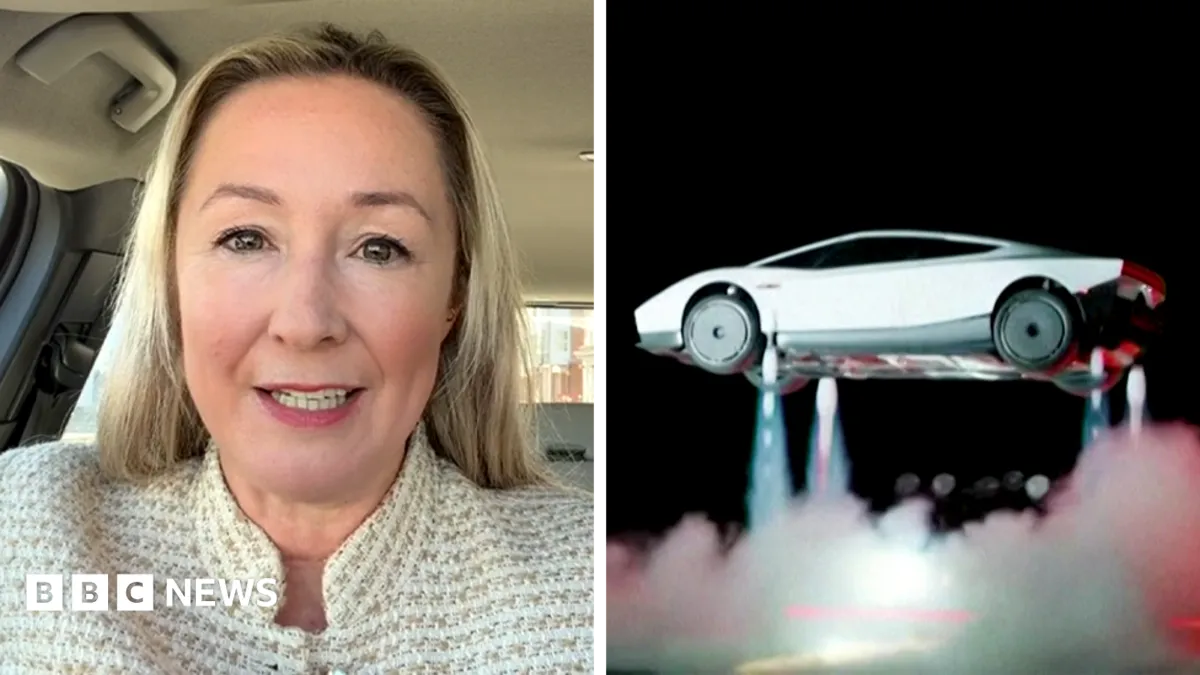
Elon Musk unveils a flying car, and SpaceX helped build it
The Tesla CEO's showcase at a SpaceX facility signals a future where road and rocket engineering converge.
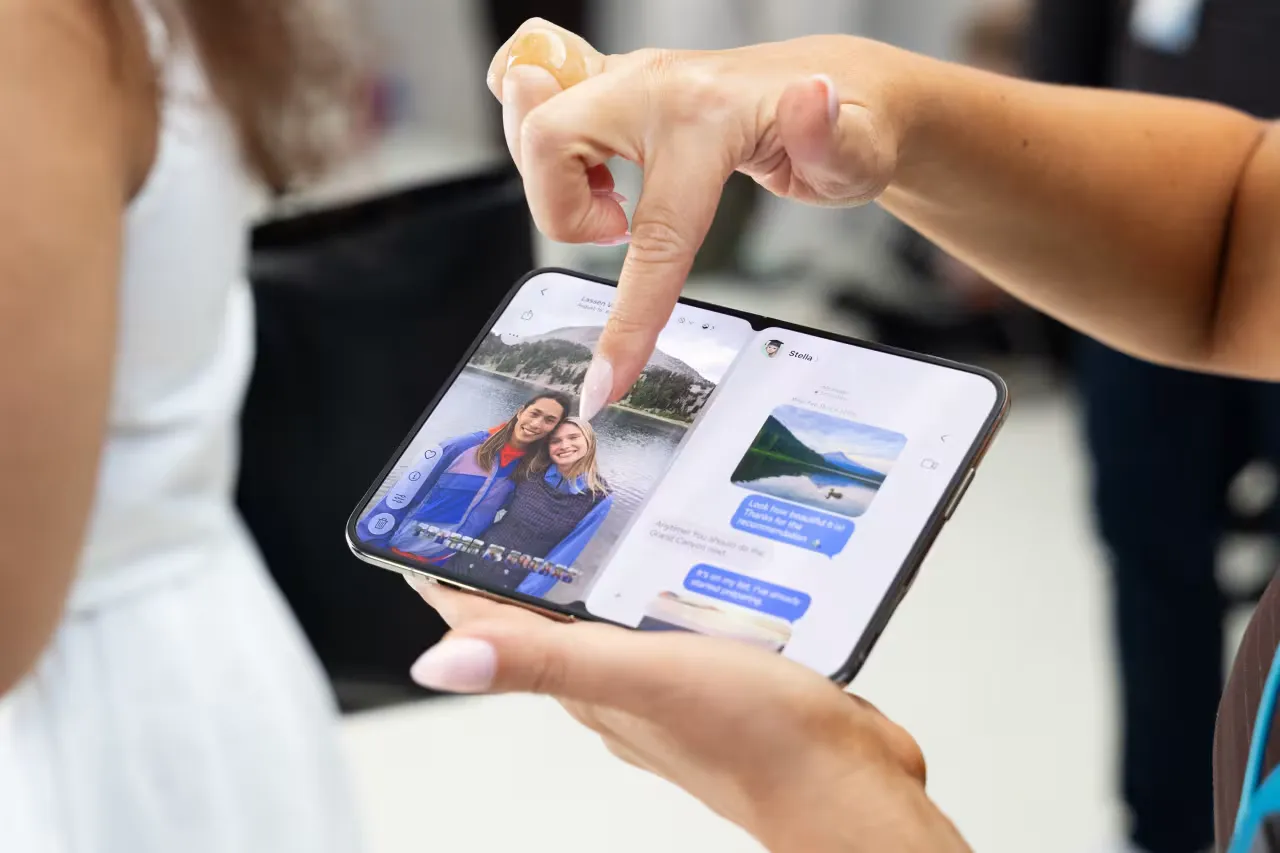
Apple's $2,000 iPhone Duo opens preorders, taking on Samsung and Google
Apple's first foldable hits the market at a premium price, reshaping a category Samsung and Google have led.

Pope Leo XIV, first American pope, diagnosed with lung cancer
The 71-year-old Chicago-born pontiff underwent successful surgery on his right lung, and his diagnosis raises new questions about his AI-focused papacy and the Vatican's future.