DoorDash's $17B Instacart Grab Unites Delivery Titans
The largest restaurant delivery service is buying the biggest online grocery platform, reshaping the on-demand economy and inviting antitrust scrutiny.
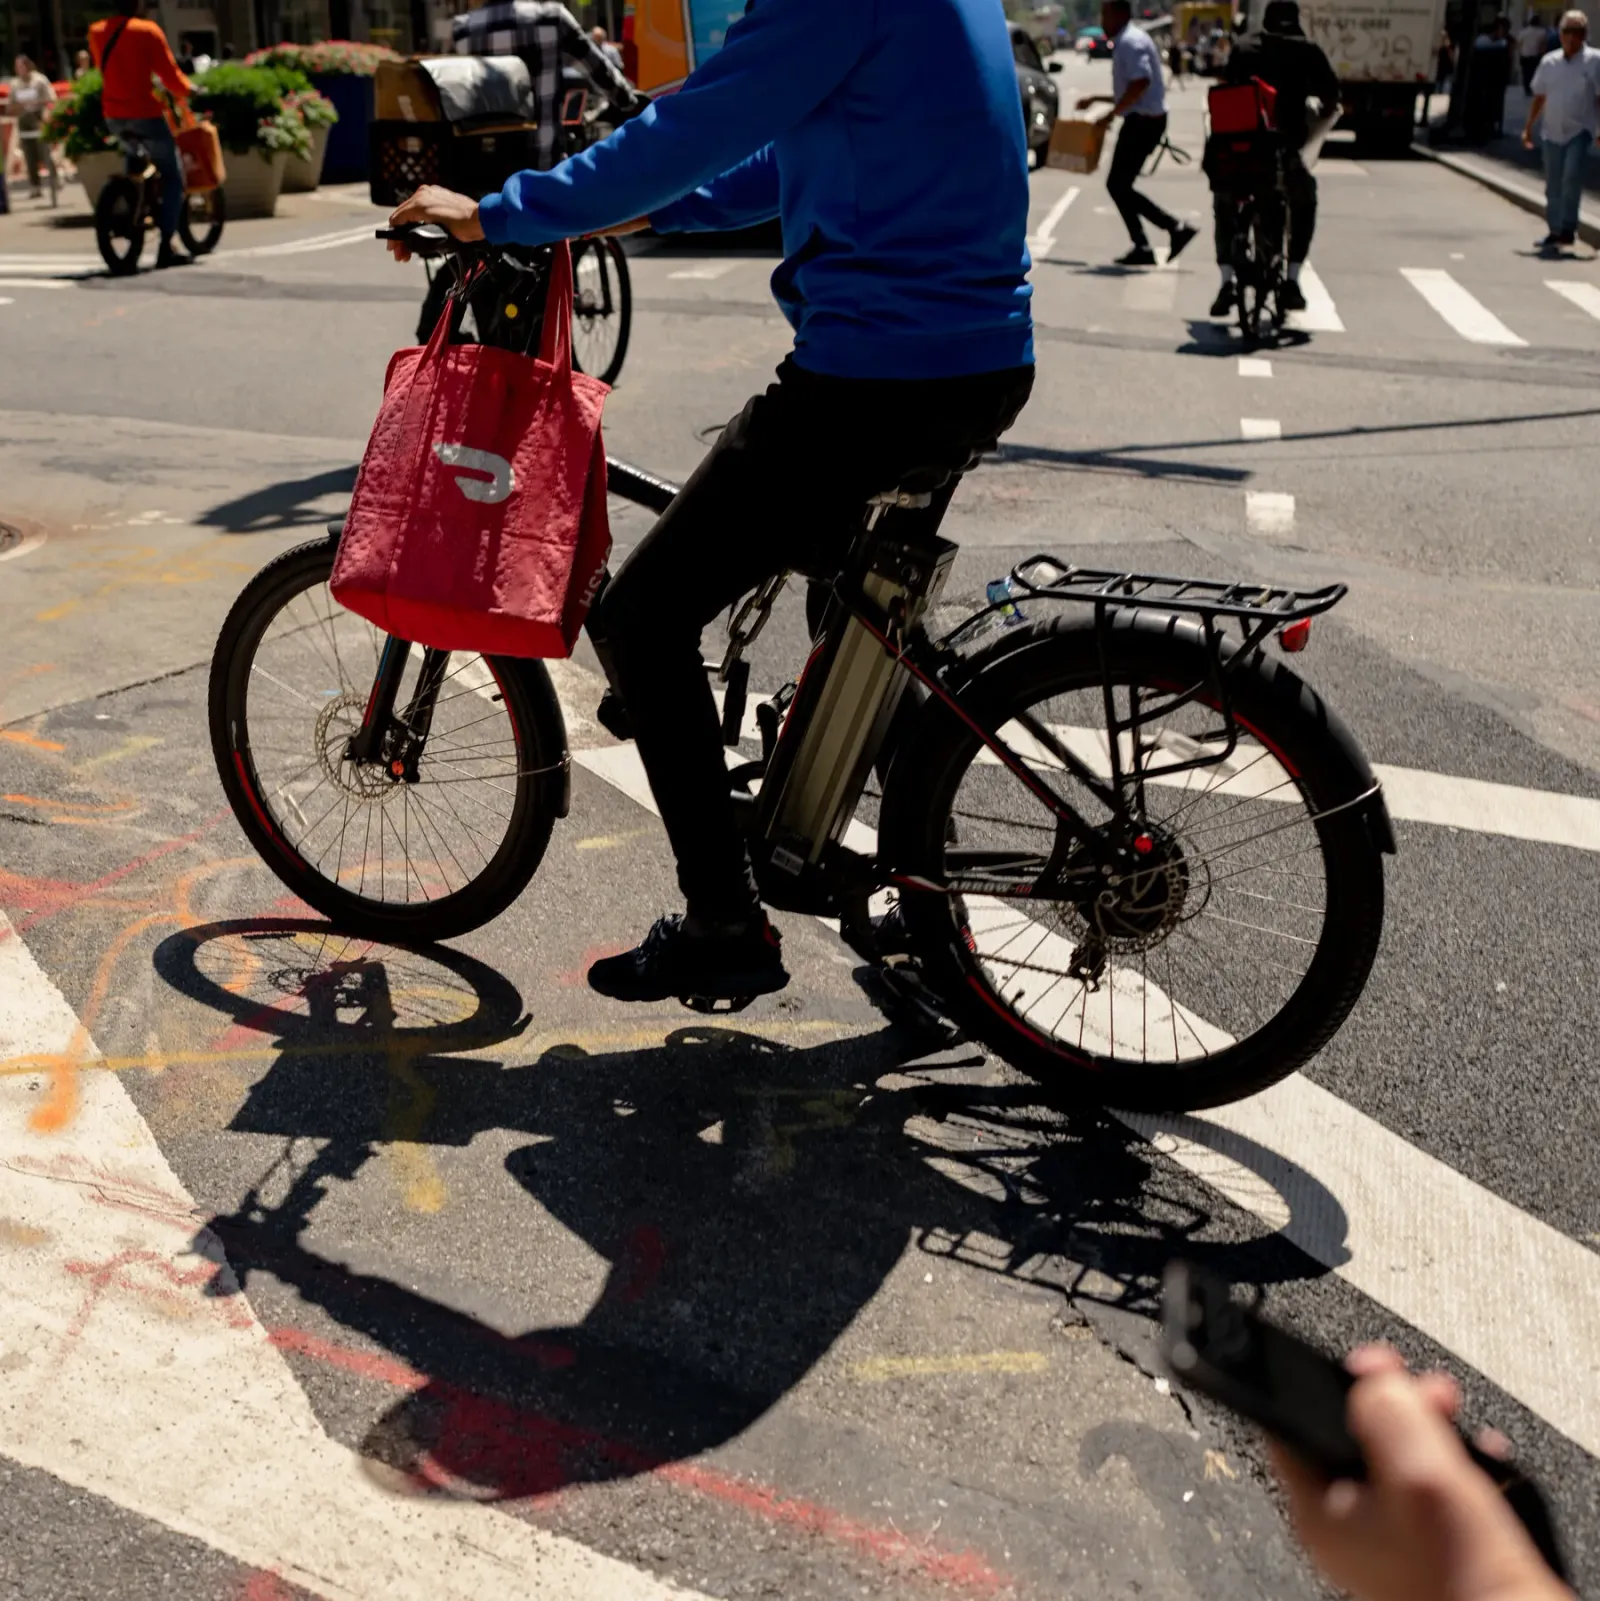
DoorDash has agreed to acquire Instacart for $17 billion, uniting the country's top restaurant delivery service with its leading online grocery platform. The deal would create a delivery super-app and likely trigger regulatory review, with major implications for competitors, gig workers, and consumers.
The $17 billion price tag is the headline, but the real story is what it buys: DoorDash, the country's largest restaurant delivery service, is acquiring Instacart, its biggest online grocery platform. The deal unites two companies that have defined the on-demand delivery era, creating a combined entity with a grip on both the meal and the grocery run. For consumers, it could mean one app for everything from a burrito to a bag of spinach. For competitors, it is a warning shot.
The numbers behind the deal are stark. DoorDash has long dominated restaurant delivery, while Instacart has built the largest network of gig workers ferrying groceries from stores like Costco, Kroger, and CVS. Together, they would control a massive share of the last-mile delivery market, with the data, driver pool, and merchant relationships to make it very hard for smaller players to compete. The $17 billion valuation for Instacart reflects not just its current business, but the strategic premium DoorDash is willing to pay to own the grocery aisle.
Why does this make sense strategically? Restaurants are a high-frequency but low-margin business. Groceries are bigger baskets, more frequent trips, and a deeper relationship with the household. By folding Instacart into its logistics network, DoorDash can cross-sell: a customer ordering dinner can add a gallon of milk, or a weekly grocery order can include a hot meal. The combined company can also optimize its driver fleet, keeping couriers busier and reducing the cost per delivery. That is the classic playbook of platform consolidation: more categories, more data, more leverage.
But the deal will not sail through. Antitrust regulators have taken an increasingly aggressive stance on tech and gig-economy mergers, and this one combines two of the most visible players in the space. The Federal Trade Commission and the Department of Justice have both signaled that they are watching labor markets and platform power. A combined DoorDash-Instacart would control a huge share of the on-demand delivery workforce, raising questions about pay, classification, and competition for drivers. Expect a long review, and possibly conditions or a challenge.
The competitive landscape is already shifting. Uber Eats has been expanding into groceries, and Amazon has been quietly building out its delivery infrastructure. Walmart has its own massive logistics operation. A combined DoorDash-Instacart would give the new entity a scale advantage that could squeeze these rivals, particularly in the grocery segment where Instacart has deep relationships with retailers. Those retailers, who currently use Instacart to reach online shoppers, may now find themselves dependent on a company that also competes with them through DoorDash's marketplace.
The financial logic is also worth scrutiny. $17 billion is a hefty price, and DoorDash will need to show that the combined company can generate real profits, not just growth. Instacart has been profitable in recent quarters, but grocery delivery remains a thin-margin business. The integration will be complex: two different driver networks, two different merchant platforms, two different sets of data. History is littered with mergers that looked great on paper and collapsed under operational weight.
For executives in adjacent industries, this deal is a reminder that consolidation can reshape a market overnight. If you are a restaurant chain, your delivery partner now also controls your competitor's grocery aisle. If you are a grocery chain, your online partner is now owned by a company that wants to sell you everything else. The strategic stakes are not just about delivery; they are about who owns the customer relationship in the on-demand economy.
The bottom line: DoorDash is making a bet that the future of commerce is one app, one logistics network, and one relationship with the consumer. If regulators let it through, the delivery landscape will look very different. If they block it, DoorDash will have to find another way to grow. Either way, the $17 billion question is now on the table, and every competitor, partner, and investor is watching.
This story's Key Insights and Take-aways are locked.
Create a free account to unlock Executive Actions for one credit.
Register to UnlockAlways free for Executives Club members. Join the Club
More in Business
Anthropic Files for IPO, Ticker 'ANT' - The AI Listing to Watch
The AI company has filed for an initial public offering under the ticker 'ANT,' giving public investors a new way to bet on the generative AI boom.

Anthropic's S-1 reveals $80.7B loss as it races OpenAI to IPO
The Claude maker files publicly for a Nasdaq listing under 'ANT,' exposing staggering losses and a world-altering ambition before it can beat OpenAI to the market.
A flaw in PHP just forced governments to pull their own sites offline
European agencies from Belgium to Germany took websites dark to patch a critical weakness in the language behind almost 70% of the web, and the blast radius extends far beyond government portals.